Filing in Colorado · Denver metro
Bankruptcy in the Denver metro, without a waiting room
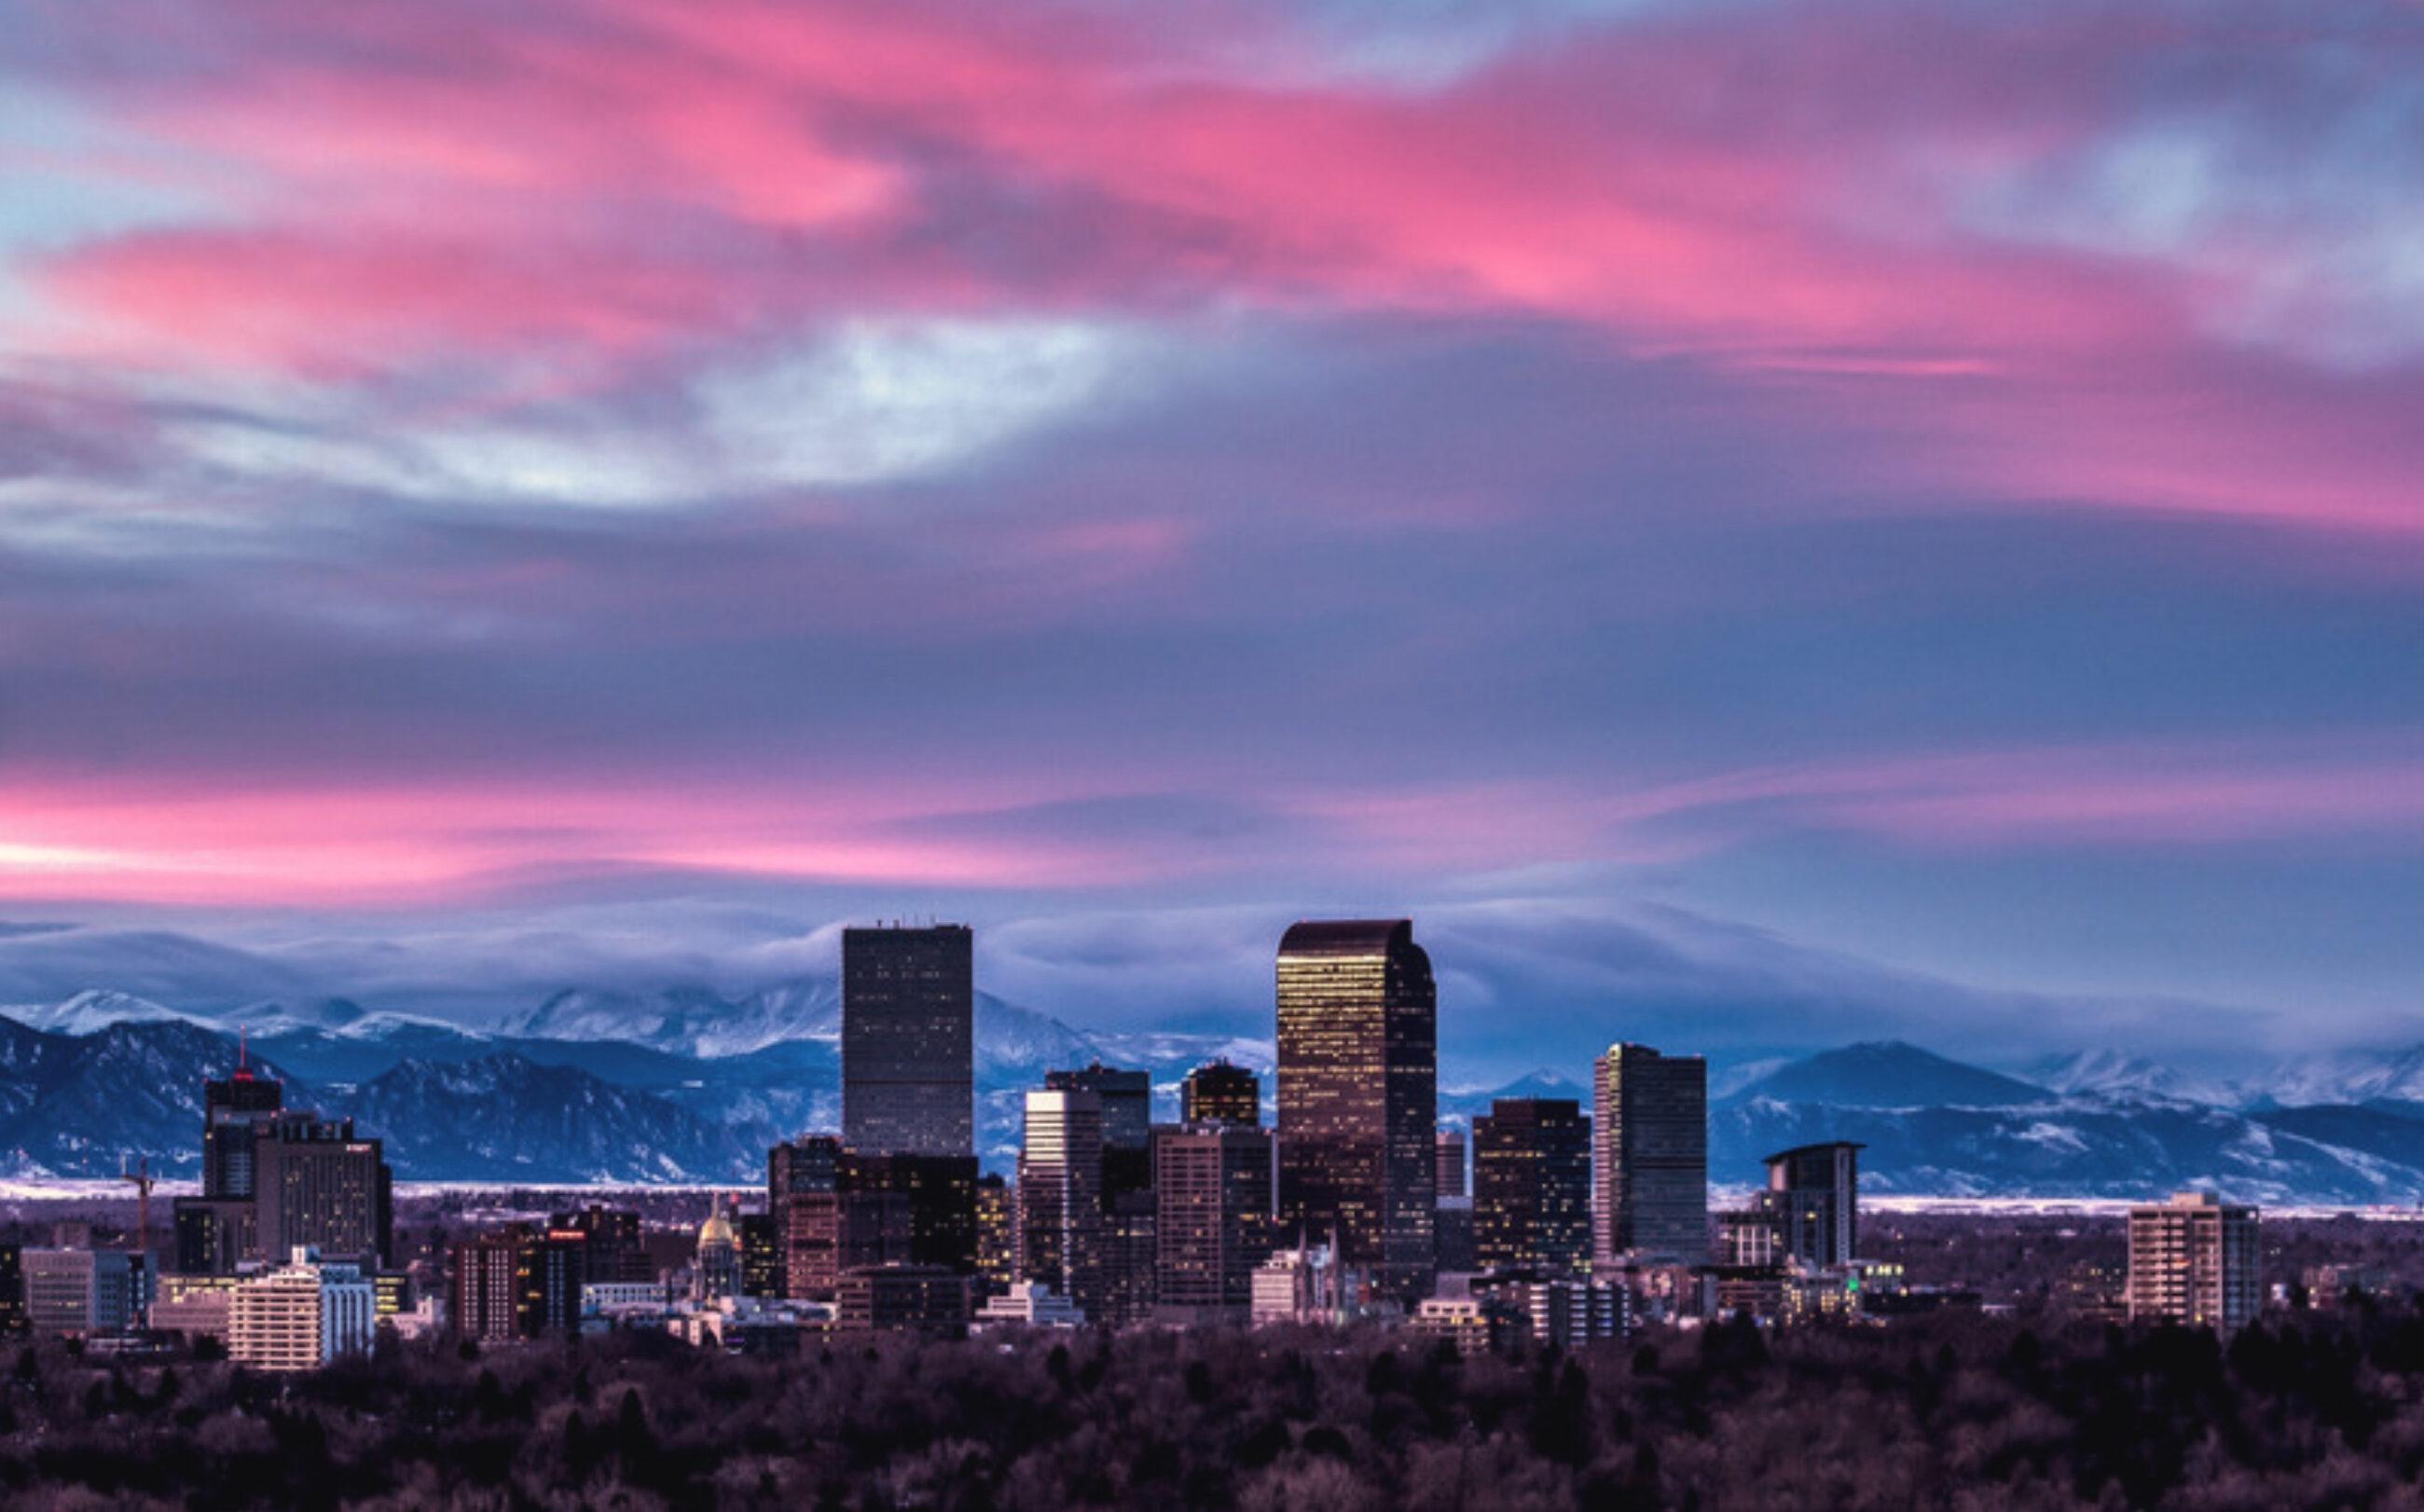
The bankruptcy court for all of Colorado sits in downtown Denver, a few blocks from the 16th Street corridor. That tends to make people in the metro assume they will be going there, and a courthouse can feel intimidating. You probably will not need to go. Your case is filed electronically, your 341 meeting happens on Zoom, and most Denver area clients finish their case without setting foot in the building.
I serve clients throughout Colorado, and there is no office to drive to. You can work with me from home, and I explain why on the firm page.
How the firm works here
You can work with me from home. Consultations, documents, and the meeting of creditors happen by phone, video, and a secure portal, so you do not travel anywhere to work with me. There is no office to visit in Denver metro.
Communities
Denver, Aurora, Lakewood, Englewood, Littleton, Arvada, Westminster, Thornton
How working from home worksWhich county am I in, for bankruptcy purposes?
The Denver metro is one court for bankruptcy but seven or so counties for everything else, and the county matters in two places. Denver is a consolidated city and county. Lakewood is in Jefferson County. Englewood is in Arapahoe County, and so is most of Littleton. Thornton is in Adams County. Arvada and Westminster each straddle Jefferson and Adams. Aurora reaches into Arapahoe, Adams and Douglas counties.
This matters more than it might seem. Your county sets the IRS housing and utility allowance in the means test, and your county court is usually where a creditor sues you.
Where are collection lawsuits filed in the Denver area?
Most consumer collection suits in Colorado are filed in county court, which hears civil claims up to $25,000, and generally in the county where you live. If you live in the City and County of Denver, that is Denver County Court, which is unusual in Colorado because it is administered by the City and County of Denver rather than by the state Judicial Branch. In Aurora it may be Arapahoe or Adams County Court depending on which side of the county line you are on. In Lakewood it is Jefferson County Court.
Being served with a lawsuit is frightening, and the paperwork looks the same wherever it comes from: a summons with a response deadline. If you miss it, the creditor can get a default judgment and then a writ of garnishment against your wages or your bank account. Filing bankruptcy stops a pending lawsuit and an active garnishment at the moment of filing, through a court order called the automatic stay.
How much of my paycheck can be garnished in Colorado?
If a garnishment is already taking part of your pay, I know how hard that makes every month. Colorado limits ordinary wage garnishment more tightly than federal law does. For most consumer debts, a creditor can take no more than 20 percent of your disposable earnings.
Support obligations and some tax debts follow different rules. And a garnishment that took money in the 90 days before you filed can sometimes be recovered, depending on the amount and the exemptions available.
What does the means test look like for a Denver household?
The Colorado median income is statewide, so a Denver household and a Grand Junction household of the same size face the same first threshold. The housing and utility allowance in the second step comes from the IRS Local Standards for your county, and Denver County's figure can differ from Adams, Arapahoe or Jefferson. Two families with the same income living a few miles apart in Aurora can get different results. The detail is in the Colorado means test explained.
What cases do I see most from the Denver metro?
Medical debt is a steady one, often from a single hospitalization that insurance did not fully cover, and it is nothing to be ashamed of. Colorado has added real protections for patients in the last several years, which I cover in medical debt in Colorado. Divorce is another: debts divided in a decree that the creditor never agreed to, and the question of whether to file before or after. That is bankruptcy and divorce in Colorado.
And student loans. The metro has a large share of the state's teachers, nurses, social workers and public employees, many of whom have been in repayment for a decade or longer. For them, student loan discharge is often the more important conversation than the bankruptcy itself.
Where else in Colorado do I help, and what is the next step?
The statewide rules, including the courthouse, trustees and exemptions, are on the Colorado page. If you live just outside the metro, please see Boulder County and Broomfield, Northern Colorado or Colorado Springs and Pueblo. If you live in the mountains or west of the Divide, see the High Country and Western Slope.
If you are still working out whether filing makes sense at all, start with how bankruptcy works and take the time you need. If you are past that, the first real conversation is a paid Strategy Session in which I look at your actual numbers and tell you honestly what I would do. This is how to set one up, and I would be glad to hear from you.
Questions
What people here ask me
Do you have an office in Denver where I can meet you?
No. I serve clients throughout Colorado. Everything happens by phone, video and a secure portal, including the 341 meeting, so you can do all of it from home.
I live in Aurora. Which court will my case be in?
Your bankruptcy case is in the U.S. Bankruptcy Court for the District of Colorado, the same as every Colorado resident. A collection lawsuit against you, on the other hand, is usually in the county court for the part of Aurora you live in, which may be Arapahoe, Adams or Douglas County.
I was served with a lawsuit from Denver County Court. Does bankruptcy stop it?
Filing a bankruptcy case stops most pending collection lawsuits immediately under the automatic stay, including one in Denver County Court. The debt itself is then usually discharged at the end of the case. Keep the summons and note the response deadline while you decide. You do not have to sort this out alone.
Is Chapter 7 or Chapter 13 more common in the Denver metro?
Chapter 7 is more common for consumer cases generally, but the answer for you depends on your income against the Colorado median, your county's housing allowance and what you own. Higher earning metro households are more often pushed toward Chapter 13.
Elsewhere in Colorado
Other regions
- Northern ColoradoFort Collins, Loveland, Greeley
- Colorado Springs and PuebloColorado Springs, Pueblo, Monument
- Boulder County and BroomfieldBoulder, Louisville, Lafayette
- The High Country and Western SlopeGrand Junction, Montrose, Delta
- Bankruptcy in Colorado, statewide →
Sources
- U.S. Bankruptcy Court for the District of Colorado, court locations
- U.S. Trustee Program, Region 19, local section 341 meeting information
- Denver County Court, civil division
- Colorado Judicial Branch, county courts
- Colorado General Assembly, HB19-1189 (wage garnishment limits)
- IRS, Local Standards: Housing and Utilities
- U.S. Trustee Program, means testing information (median income and IRS standards)
You do not have to figure this out alone.
From the first call, you will be treated with kindness and respect, and without judgment. You can call my office or book a Strategy Session yourself, and no one will pressure you.